Branches & ATM/CDM

News - Events
Back to previous

How much do you need to start saving?

There is no one-size-fits-all amount. Start with your cash flow, emergency reserve and near-term goals to build a savings habit instead of waiting until you have plenty of money.
How Much Should You Save Before You Start?
In the first few years of working, when income may be limited and many expenses lie ahead, saving can feel like a goal to postpone until you earn more. In reality, the most important step is often to begin with an amount you can maintain. So how much should you save, and where should you start?
Understand your cash flow first
Before setting a savings target, review your income and expenses. Record essential costs such as housing, food, transport and bills, as well as discretionary spending and existing debt repayments. This will show how much is available after regular commitments and where adjustments may be possible. If your income fluctuates, use a conservative estimate and avoid building a plan around occasional bonuses or unusually strong months. A budget based on actual cash flow is more likely to be sustainable.
Start with an emergency reserve
An emergency fund is often the first savings priority because it helps cover essential expenses when unexpected events occur. A common guideline is to build a reserve equal to three to six months of essential living costs, although the appropriate amount depends on job stability, dependants and other circumstances. You do not need to reach the full target immediately. Begin with a smaller milestone, such as one month's expenses, and increase it gradually. Keep the funds accessible and separate from money set aside for planned purchases or investments.
Build a consistent habit around clear goals
Once you have a basic reserve underway, set specific goals for the next 12 months and beyond. These may include education, travel, a vehicle or a home deposit. Decide how much each goal requires and when you will need the funds, then choose a savings method that matches the time horizon. Automating a transfer after payday can help make saving a regular commitment rather than an afterthought. Review the amount as your income changes, but avoid setting a target so high that you need to withdraw the money again before month-end. Consistency matters more than starting with a large amount.
OCB offers solutions to help you manage daily finances and develop a savings habit:
✨ OCB Payment Account: Manage incoming funds and everyday transactions conveniently.
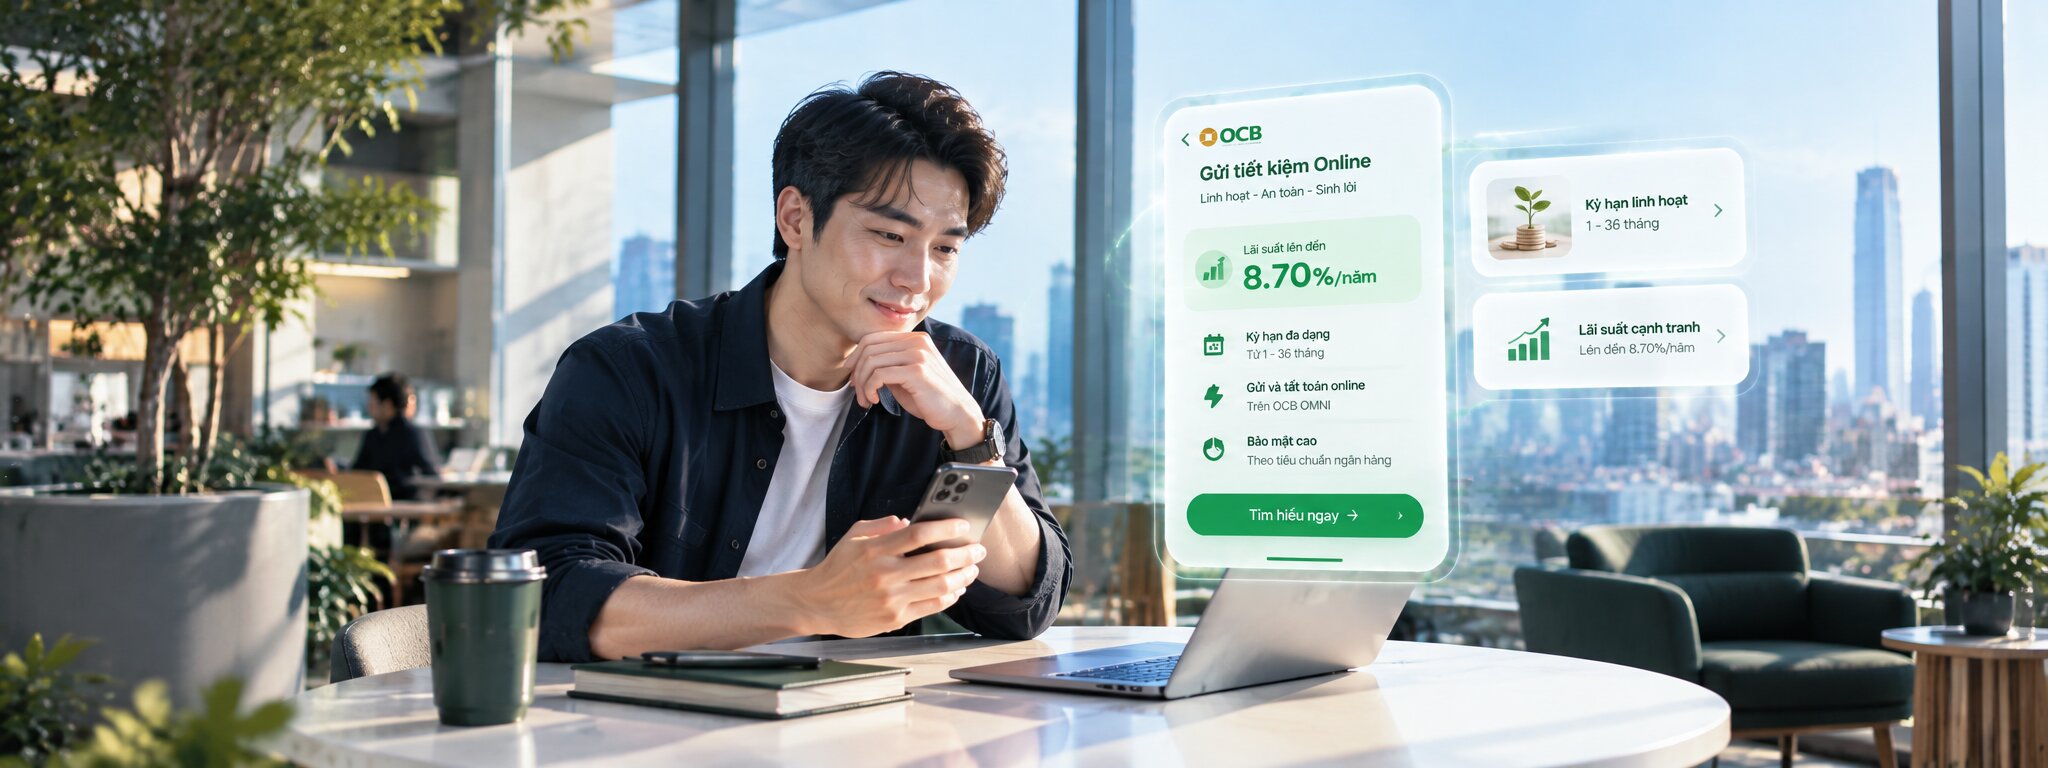
✨ OCB Online Savings: Build savings through digital banking, subject to the applicable product terms.
✨ OCB Mastercard Passport: Make everyday payments with an international debit card and enjoy eligible card benefits.
Through the OCB OMNI app, you can manage your account, monitor transactions and access banking services in one place.
There is no universal savings figure that works for everyone. Start with what your cash flow allows, build a reserve step by step and let consistency turn small contributions into progress.
Related news
See more