Branches & ATM/CDM

News - Events
Back to previous

As Your Income Grows, Which Priorities Should Change?

Higher income creates more options—from further education and a new home to supporting your family. How can you reset your goals so that a better lifestyle does not come at the expense of financial freedom?
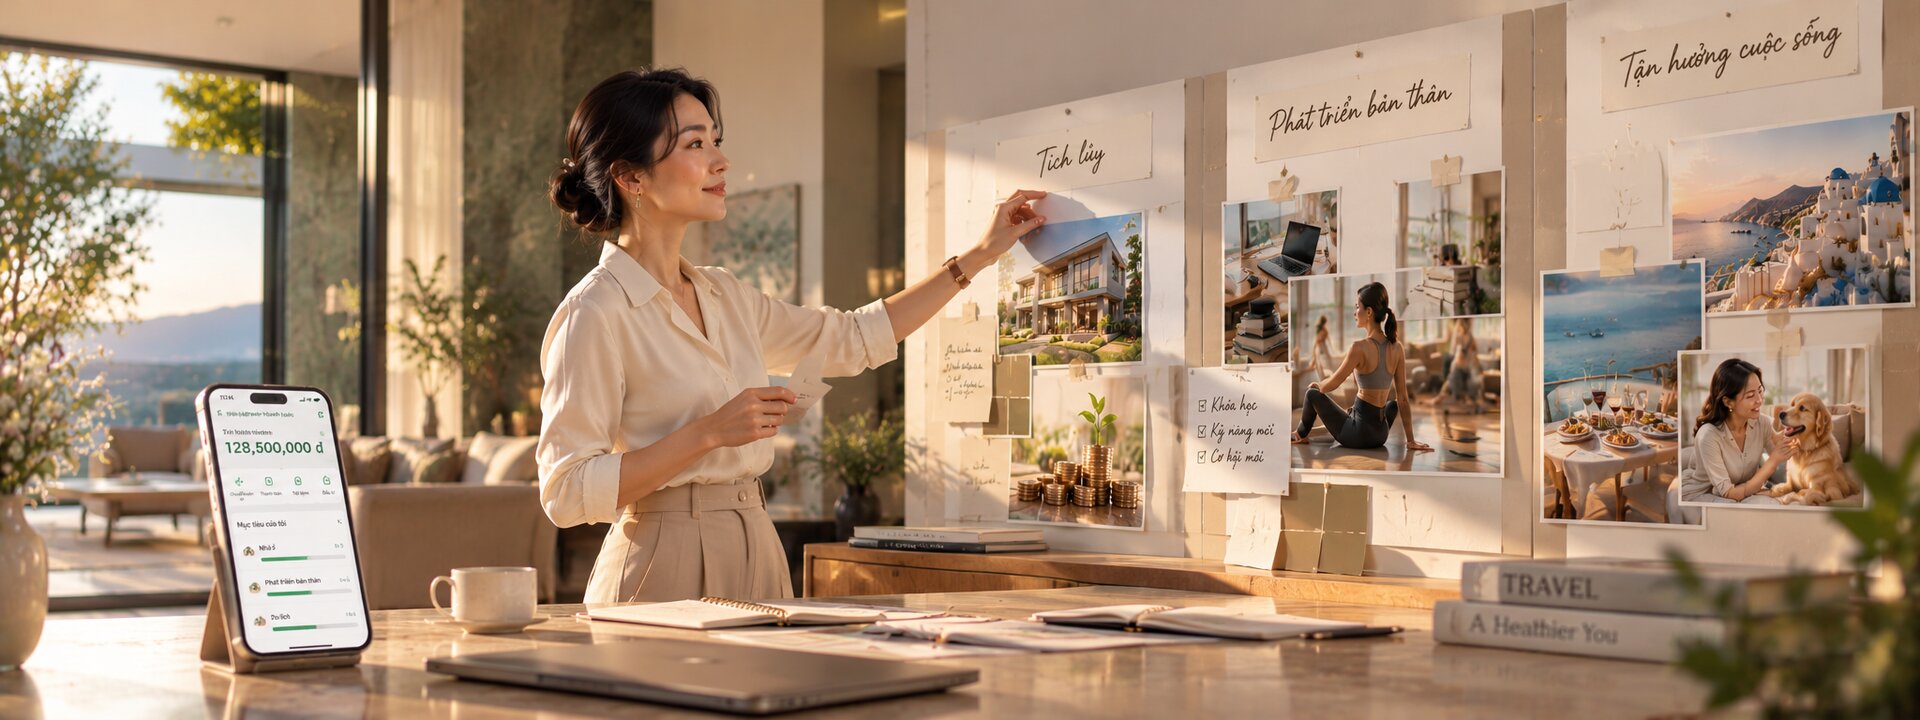
An increase in income can come from career advancement, a side business, stronger business performance or proceeds from an asset. Whatever the source, having more money available creates new choices. The challenge is deciding how to use that additional income without allowing spending to grow at the same pace.
Review your financial priorities
When income rises, take the opportunity to review your financial goals rather than immediately increasing day-to-day spending. Revisit essential expenses, outstanding debt, emergency savings and longer-term plans such as buying a home, education or retirement. If you have high-interest debt, consider reducing it before committing to new recurring expenses. You may also want to increase your emergency reserve if your household responsibilities have grown. A clear priority list helps ensure that each additional amount contributes to something meaningful.
Allocate additional income with intention
A practical approach is to divide the increase in income among several purposes: improving your quality of life, building savings and investments, and preparing for future commitments. The proportions will depend on your circumstances, but setting them in advance can help prevent impulse spending. For example, you could automate a transfer to savings as soon as your salary arrives, then use the remaining amount for planned spending. Review subscriptions, insurance premiums and other recurring commitments to make sure they still provide value. The aim is not to avoid enjoying your income, but to make sure that lifestyle upgrades remain affordable over time.
Make room for flexibility and future opportunities
As your financial position improves, your goals may also become more ambitious. You may consider investing, starting a business, supporting your parents or preparing for your children's education. Before committing funds, assess the time horizon, liquidity needs and risks involved. Keep short-term reserves separate from long-term investments, and avoid concentrating too much of your wealth in a single asset or opportunity. Review your plan regularly so that it reflects changes in your career, family and market conditions.
To help you manage growing income and plan for future goals, OCB accompanies you with:
✨ Current Account: A convenient way to manage incoming funds, payments and everyday transactions.
✨ Flexi Savings: A flexible savings solution to help you put funds to work while retaining the ability to transfer your certificate of deposit when needed, subject to product terms.
✨ OCB Mastercard World 2in1: An integrated credit and debit card offering premium payment features and privileges.
A higher income can improve your quality of life, but lasting financial progress comes from using that income with purpose. The right balance allows you to enjoy today while continuing to build choices for tomorrow.
Related news
See more